Unpaid Severance Pay to Be 'Blocked at the Source'... Retirement Income Security and Higher Returns Put to the Test
Mandatory for all workplaces by 2030
New fund-based plans managed by professional firms
Retirement security through "automatic pension payments"
The government’s announced plan to reform retirement pensions is the first structural overhaul in more than 20 years, since the system was introduced in 2005. The aim is to transform a retirement benefit system focused on preventing unpaid benefits into one that also improves returns through professional management and secures retirement income.

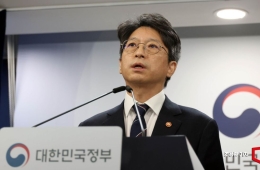
Kim Younghoon, Minister of Employment and Labor, delivers opening remarks at a ruling party-government meeting on pending issues related to the Climate, Environment and Labor Committee at the National Assembly Members' Office Building on the 29th. 2026.10.29 Photo by Yoon Dongju
View original image"Workplaces can switch from contract-based plans to fund-based plans and back"
The centerpiece is the introduction of fund-based retirement pensions, in which professional trustee corporations pool and manage contributions from multiple participants. Financial institutions, labor-management organizations, and public institutions can serve as managers, giving participants a choice between the existing contract-based plans and fund-based plans. The goal is to reduce the burden on individual participants of choosing investment products themselves and improve management efficiency through economies of scale, pooling funds and diversifying investments. However, introducing fund-based plans does not guarantee better returns. The system’s success is expected to depend on investment performance, fees, and the accountability and oversight framework for trustee corporations. The government has also introduced safeguards for participants by strengthening the burden of proof for trustee corporations in damages claims and requiring them to set aside 0.25% of pension assets as an operational risk reserve. Nam Seonguk, director of the Retirement Pension and Welfare Division at the Ministry of Employment and Labor, explained, "Workplaces that have already adopted existing contract-based defined contribution (DC) plans can switch to fund-based plans or return to contract-based plans if they reach an agreement between labor and management and reflect it in their plan rules."
Making external funding mandatory is a safeguard intended to reduce unpaid severance benefits. Last year, severance pay accounted for 41.1% (823 billion won) of all unpaid wages. If companies record severance pay only as a liability on their books, workers face a high risk of not receiving their benefits if a company goes bankrupt or shuts down. Once external funding is made mandatory in stages, retirement benefit funds will be deposited with financial institutions and can be protected independently of the company’s financial deterioration. However, the requirement will apply only to periods of continuous service beginning on or after the effective date of each stage; it will not be retroactively applied to all previous periods of service.

“500 trillion won in retirement pensions” heads to capital markets... A test for improving returns
The capital markets are also expected to see considerable change. Retirement pension assets had grown to 501.4 trillion won at the end of last year. The rate of return rebounded to 6.47% last year, but remained well below the National Pension Service’s 18.82% return. The introduction of fund-based plans could broaden the investment options for retirement pension funds if it spurs professional management and diversified investment, while limits on IRP investments in risky assets are eased and investments in comprehensive investment accounts (IMAs) and short-term notes are permitted. The system could also develop into one that professionally manages long-term funds, like Australia’s superannuation system or the UK’s National Employment Savings Trust (NEST). However, as expanding the range of investments could increase the risk of losses, risks and fees must be considered alongside returns.
Hot Picks Today
 The Era of Getting 200 Million Won After 30 Years Is Over... A Japanese Bank's "Perpetual Department Head" Who Just Clocked In Cries Out
- "They Blocked China's Chips, and It Became a 'Value-for-Money Monster'..." China's Counterattack, Copying the U.S. and Selling It for Peanuts [China Shock, K-Industry on the Brink | AI] 1
- "Could That Really Be a Teacher at Our School?"... Japanese Teacher Caught Appearing in Adult Video Gives Bizarre Explanation
- "Poured Gasoline and Fled": Yeoksam Arson Suspect Transferred in Custody, Charged with Attempted Murder (Comprehensive)
- "Two Spend 500,000 Won in a Flash, Yet Wait Two Hours?" ... 'Dreamland' Shunned by Kids and Foreign Tourists
Liquidity pressure on small businesses... Support for a smooth transition is key
On the other hand, small businesses may face a greater burden from having to deposit retirement benefits externally. The rate of retirement pension adoption among businesses with fewer than five employees is only 10.6%. Companies with limited cash may come under liquidity pressure as they deposit funds for retirement benefits with external institutions monthly or annually. The government plans to provide matching contributions and interest subsidies on loans to workplaces that adopt the system early, before it becomes mandatory. As the requirement will be extended to businesses with fewer than 10 employees by 2030, the challenge will be to ensure adequate support in terms of scale and duration, as well as acceptance on the ground. Shin Jinyoung, a professor at Yonsei University’s School of Business, said, "If small businesses are exempted because of their limited ability to pay, the most vulnerable people, who have the greatest need for severance pay protection, will instead be excluded. The system should apply universally, while financial support should be provided to cushion the impact on small businesses."

© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.