JPMorgan: "CoreWeave's Business Remains Sound Despite Debt Concerns"
Analysts say CoreWeave's rising debt and rapid cash burn are the result of its aggressive business expansion. Since the issue is not the profitability of individual projects, they say market concerns about the company are excessive.

According to Bloomberg on Oct. 19 (local time), JPMorgan assessed CoreWeave's business model in these terms, saying it "remains sound." JPMorgan analysts including Samik Chatterjee cited strong demand for AI computing and long-term take-or-pay contracts. These contracts allow the company to secure customers before new facilities become operational, they said.
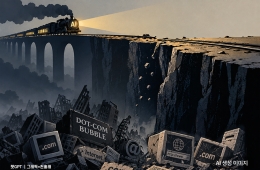
The analysis came as CoreWeave's share price recently plunged. The company has taken on substantial debt to expand its business, and rising bond yields have heightened concerns about its financial health. Investor sentiment was also weakened by market research firm Gartner's questions about whether AI revenue can generate returns commensurate with massive infrastructure investments.
JPMorgan estimates that the unlevered internal rate of return (IRR) on CoreWeave's typical five-year contracts will be in the mid-teens. That is above the company's average cost of capital of 9% to 11%. In other words, the business itself remains profitable despite its debt burden. JPMorgan said, "Beyond the sound economics of a typical five-year contract project, the company can generate additional revenue by re-contracting the GPUs after five years."
JPMorgan also said CoreWeave's contract structure helps mitigate debt risk. Even under conservative assumptions, about 51.0% of the value of a five-year contract is spent on capital expenditures, with about 80.0% of that amount financed through asset-backed debt, according to JPMorgan. It estimates that after repaying this debt, cash equivalent to about 16% of the contract value will remain. This would be enough to cover data center-related costs for about five years, even if the contract is not renewed.
However, CoreWeave's aggressive expansion is expected to weigh on cash flow for the time being. JPMorgan estimates that once facilities are fully operational, each gigawatt (GW) of capacity could generate $10 billion to $15 billion in annual revenue. But it estimates that adding 1 GW of capacity requires more than $35 billion in upfront investment.
Hot Picks Today
 Selling Like Crazy Every Year... 30-Year-Old Hetbahn Takes on a New Challenge: Tastes Better Than "Mom's Home Cooking" [On-Site Report]
- A 12-Year-Old Girl Went to the Hospital After Her Blood Pressure Hit 225 and Was Stunned: "What Is This Coral Reef-Like Thing in Her Aorta?"
- "Hey, Lady, Teach Your Kids to Behave!" ... 300,000 Won in Cash and a Bodily Injury Claim Demanded Over Child's Door Ding
- Yongin Mayor Lee Sangil: "56 Billion Won for Singal's Development... Shared Platform Construction to Begin in December"
- I Thought Only 'Old Guys' Ate It... Young People Are Hooked on This 'Unusual Food' at Risk of Disappearing? [Delicious Stories]
JPMorgan said, "CoreWeave's cash burn is driven less by the profitability of individual projects than by the fact that annual new capacity additions are large relative to its currently operational facilities." It nevertheless expects that by 2030, operational capacity will be four to five times the amount of new capacity added annually, allowing the company to offset expansion costs with internally generated cash.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.