[Click e-Stock] "Shinsegae's Investor Sentiment Hit by Stronger Won... Target Price Cut"
Korea Investment & Securities lowered its target price for Shinsegae on Friday, October 16, from 750,000 won to 530,000 won, saying the stronger won had dampened investor sentiment. It maintained its “Buy” rating.
“We are lowering our target price by 29.3% from the previous level to reflect lower earnings estimates for department stores and duty-free shops, as well as a valuation adjustment,” said Kim Myung-joo, an analyst at Korea Investment & Securities. “The won began strengthening in July, leading to a recovery in outbound demand, while foreign sales in the department store industry declined. As a result, valuations fell sharply, bringing the 12-month forward price-to-earnings ratio (PER) down to around 5.6.”
Shinsegae’s consolidated results for the third quarter of this year are expected to meet market expectations, with revenue up 9.4% year on year to 1.7896 trillion won and operating profit up 76.5% to 176.1 billion won. “It is true that sales momentum in the department store industry has slowed more than we expected when we reported second-quarter results. Even so, same-store sales growth at Shinsegae’s department stores in the third quarter is expected to be around 15% based on managed gross sales, while operating profit is expected to reach 110.6 billion won, indicating solid performance,” Kim said.
Duty-free sales are expected to fall 21.2% from the second quarter, while operating profit is projected to decline 19.6% to 26.8 billion won. Shinsegae International, a major subsidiary, is estimated to post operating profit of 7 billion won, 21.3% below market expectations, due in part to a deterioration in its cost ratio amid the stronger won.
Hot Picks Today
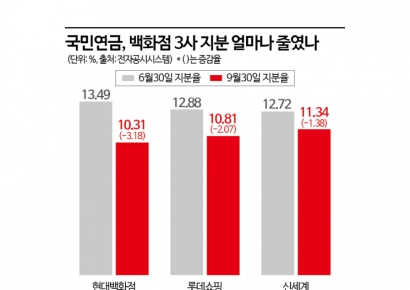 'Big Investor' NPS Has Already Cut Its Losses... Sold Department Store Stocks in Q3 Despite Strong Earnings Outlook
- "There's a Drink Like This?"... Chinese Beverage With "Korean" in Its Name Rakes in 85 Million Won in Monthly Sales
- "Samsung Electronics at 70,000 won, SK hynix at 200,000 won"... Why the gloomy outlook despite 'record-breaking earnings'?
- "I Put in 10 Million Won, but Only 2 Million Won Is Left" ... 77% Plunge Leaves Retail Investors in Samsung Electronics and SK hynix Leveraged ETFs Crying Out
- "The leggings are all see-through. It's so embarrassing to look at," complaints prompt Lululemon to fire development staff.
Although the pace of growth in the share of sales to foreign customers is expected to slow, inbound momentum remains solid, according to the analyst. “The share of sales to foreign customers in the department store industry, which had steadily increased quarter on quarter in the first half, is estimated to have shown little growth in the third quarter. This was because the won’s continued appreciation since July reduced foreign visitors’ purchasing power,” Kim said. “Fortunately, the number of inbound visitors to Korea has remained steady, and this trend is likely to continue next year.” He added, “Although the share of sales to foreign customers will grow more slowly than in the past, it is expected to resume an upward trend after bottoming out in September, thanks to the still-solid inbound momentum.”

© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.