"Overseas Subsidiary Growth Lifts COSMAX; Target Price Raised" [Click e-Stock]
Samsung Securities raises target price from KRW 270,000 to
KRW 370,000
Samsung Securities maintained its Buy rating on COSMAX on October 8 and raised its target price to KRW 370,000 from KRW 270,000.
“We raised our full-year 2027 operating profit estimate by 14% as operating leverage continues to expand at both domestic and overseas subsidiaries,” said Jung Donghee, a researcher at Samsung Securities.

Jung gave a positive assessment of COSMAX’s results for the third quarter of this year. He forecast revenue of KRW 818.6 billion and operating profit of KRW 78.9 billion, exceeding market expectations by 7.1% and 16.5%, respectively. By region, he projected revenue of KRW 560.7 billion in Korea. Despite fewer working days, he expects the company to overcome its usual seasonality and continue sequential growth, supported by solid growth among major domestic skincare clients, newly secured orders for new products from color cosmetics clients, and growth in direct exports to overseas clients. In the United States, revenue is projected at KRW 64.6 billion, with structural growth in demand for new skincare formulations expected to be confirmed for a second consecutive quarter. China, Indonesia, and Thailand are also expected to achieve full-year growth, led by new clients.
Hot Picks Today
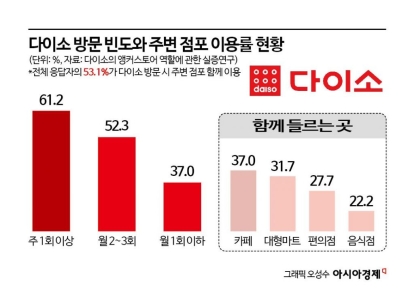 [Exclusive] Daiso Draws Shoppers for "3,000-Won Cosmetics"... and Also Boosts Sales at Nearby Olive Young
- Samsung Electronics Opens Era of KRW 100 Trillion Quarterly Operating Profit... First Ever Among Global Tech Firms (Updated)
- U.S. Senator Visits Hanwha Ocean's Geoje Shipyard... Strengthening 'MASGA' Cooperation
- Woman Buys All 196 Apartment Parking Spaces, Installs Locks... Then Faces Lawsuit
- "South Korea's Rep, Born in 1991, Is 35"... 'Married or Divorced? Still OK': Miss Universe Removes Age Limit
“Alongside increased operating leverage across all subsidiaries, we forecast an operating margin of 9.6%. Net margin is expected to grow more slowly than operating margin, reflecting approximately KRW 10 billion in non-cash, non-operating expenses related to the repurchase of a stake in COSMAX East,” Jung said.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.