[Energy Odyssey]⑨Restarting Even Accident-Stricken Reactors... AI Ignites the 'Nuclear Renaissance'
Ⅱ. Overcoming the Energy Crisis Through Technological Innovation
U.S. Big Tech Restarts Shuttered Nuclear Plants, Including TMI
From the Oil Shock of the 1970s to AI-Driven Electricity Demand, Nuclear Power Is in Demand Once Again
Fifty Years Since Kori Unit 1: The Rise of Korean Nuclear Exports to the UAE and Czech Republic
As the 12th Basic Plan Approaches, Focus Turns to Nuclear’s Role—Spent Fuel Management Remains a Challenge

Artificial intelligence (AI) is breathing new life into nuclear power plants. Major U.S. tech companies—including Google, Microsoft (MS), Amazon, and Meta—are teaming up with the nuclear industry in a bid to secure the vast amounts of electricity required for data centers. The strategy goes beyond building new reactors. Even nuclear plants that were previously shuttered are being brought back online to supply power for AI. The U.S. government is pursuing policies to dramatically expand nuclear capacity, while France, the United Kingdom, and other European countries are also witnessing a surge in nuclear construction efforts. After a long standstill, the global nuclear industry is beginning to move again.
Notably, the current situation closely resembles events from about 50 years ago. In the 1970s, two oil shocks prompted governments to turn to nuclear power. As oil supplies faltered and prices soared, countries began building reactors to reduce dependence on specific regions and fuels. Today, energy security—brought back to the forefront by the Russia-Ukraine war and the United States-Iran conflict—is being further compounded by the race toward carbon neutrality and the sharp increase in electricity demand from AI. While the world turned to nuclear power due to an oil shortage 50 years ago, today the challenge is securing enough power even for AI applications.
Korea is also at the center of this trend. While energy import dependence remains high, demand for electricity is rapidly increasing, in particular due to the semiconductor and AI data center industries. Under the 11th Basic Plan for Long-term Electricity Supply and Demand, construction has already been slated for two new large-scale reactors and one small modular reactor (SMR), with further policy discussions about the role of nuclear power after 2040 taking shape ahead of the 12th plan's announcement.
Even the TMI Accident Site Returns... Nuclear Clocks Reset by AI
On October 4, the industry pointed to Three Mile Island (TMI) in Pennsylvania, U.S., as the most dramatic symbol of nuclear energy’s resurgence. The 1979 accident at TMI Unit 2 marked a major turning point, leading to a steep decline in the American nuclear industry.
The incident began with a minor technical malfunction. On March 28, 1979, an issue in the feedwater system caused the reactor at TMI Unit 2 to automatically shut down. However, the pressure relief valve, opened to reduce reactor pressure, failed to close, allowing coolant to leak out. Operators did not recognize the problem in time, resulting in a partial meltdown of the reactor core.
Although there was little radioactive material released into the environment and no confirmed impact on resident health, the psychological blow to the nuclear industry was substantial. Fears grew that even the largest nuclear plants could face catastrophic accidents if equipment malfunctions were combined with operational errors, causing the launch of new U.S. reactor projects to plummet. The 1986 Chernobyl accident further chilled global interest in new nuclear investments.
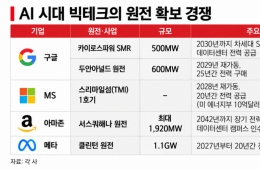
Yet, nearly half a century later, the same nuclear complex is now a symbol of nuclear renaissance. Microsoft has brokered a deal to restart TMI Unit 1, which has been offline since 2019, to supply power for 20 years starting in 2028. The U.S. Department of Energy is providing a USD 1 billion loan to support the restart. The site that shifted the global nuclear industry’s trajectory in the 1970s is now emblematic of the revival of nuclear energy in the AI era.

TMI’s return is seen as a sign that the global nuclear industry has come full circle and entered a new phase. Whereas the oil shocks of the 1970s triggered a nuclear boom but the TMI accident halted its expansion, half a century later, the call for nuclear is being driven anew by energy security, carbon neutrality, and soaring AI-driven electricity demand. Attitudes toward nuclear power are once again shifting worldwide.
Besides Microsoft, other big tech firms are also striving to lock in nuclear-powered electricity. Google has partnered with SMR developer Kairos Power to build a next-generation 500MW SMR facility by 2030 to supply its data centers. The Duane Arnold nuclear plant in Iowa is also scheduled to come back online in 2029, with Google planning to buy 600MW of power for the next 25 years.
Amazon has acquired a 960MW data center campus connected to the Susquehanna nuclear plant in Pennsylvania for USD 650 million, signing a long-term contract to receive up to 1,920MW through 2042. It has also invested USD 500 million in SMR developer X-Energy. Meta, meanwhile, has arranged to purchase power from Illinois' Clinton nuclear power plant for 20 years starting in 2027.
Beyond Big Tech: U.S. and European Governments Also Push for More Nuclear
The AI-driven battle to secure electricity is fueling a new surge in nuclear investment—rooted in the unique requirements of data centers. Not only do these facilities consume vast amounts of electricity, they must also operate servers 24/7, thus requiring stable, reliable energy supplies. With the competitiveness of AI increasingly determined by the ability to provide steady, on-demand power—rather than mere cost efficiency—robust generation sources are now vital.
It is not only big tech companies pushing the momentum—the gears of government policy are turning as well. In November 2024, the United States unveiled a roadmap to triple nuclear capacity by 2050, and in May of the previous year announced policies to quadruple it. Alongside new construction, efforts are underway to extend operations for existing reactors, restart closed plants, and accelerate SMR development.
This trend is mirrored in Europe. France has scrapped its post-Fukushima plan to reduce nuclear dependence and is now planning six new nuclear plants, with eight more under review. The UK plans to expand nuclear capacity from roughly 7GW to 24GW by 2050. Sweden has lifted a ban that previously restricted new reactors to existing sites and capped the country at 10 reactors.
Even Germany, once considered the hallmark of a nuclear phase-out, is reassessing its stance. In January, German Chancellor Friedrich Merz called the country’s nuclear retreat a “grave strategic mistake,” suggesting that Germany could have maintained more power generation capacity had its last reactors stayed online. Although Germany shuttered its final nuclear plants in 2023, it has since stepped back from its opposition to nuclear projects in other nations.
Korea Chose Nuclear Amid the Oil Shock... Now an Exporter after 50 Years
The return to nuclear is even more familiar territory for Korea. Korea first embarked on nuclear development as a response to energy security concerns—though in the 1970s, it was the threat of oil shortages, not AI, that drove the decision.
The twin oil shocks of the 1970s shattered the illusion that oil would always be plentiful and cheap. For Korea, then rapidly advancing its heavy chemical industries, the impact was particularly severe. Steel, petrochemicals, and shipbuilding—industries that consume tremendous energy—were booming, but domestic energy resources were scarce. Surging global oil prices repeatedly threatened the nation’s industrial and economic competitiveness.
Amid growing calls to diversify energy sources, nuclear entered the spotlight. Commercial operations for Kori Unit 1 began in 1978, but at that time, Korea relied on foreign technology for reactor design and core equipment. With continued plant construction, however, Korea gradually acquired the capacity to design, manufacture major components, build, operate, and maintain nuclear plants domestically.
The global nuclear industry’s growth was anything but smooth. After the TMI accident came the 1986 Chernobyl disaster in the former Soviet Union and the 2011 Fukushima disaster in Japan, each reigniting safety debates. Germany and several other countries opted to phase out nuclear; the new reactor market stagnated for years.

Korea, meanwhile, continued building experience in constructing and operating reactors. The result: the APR1400, a Korean-designed 1,400MW-class nuclear plant. The APR1400 secured EUR (European Utility Requirements) certification in 2017, and earned design certification from the U.S. Nuclear Regulatory Commission (NRC) in 2019. By 2023, Korea’s export-oriented APR1000 was also awarded EUR design certification for Europe.
This accumulation of technology led to exports. In 2009, Korea won the Barakah nuclear plant contract in the UAE, and last year achieved a breakthrough in the European market. Korea Hydro & Nuclear Power was chosen as the preferred bidder for the Czech Republic’s Dukovany new nuclear project in 2024, and after roughly eight months of negotiations, signed the EPC (Engineering, Procurement, and Construction) contract for Dukovany Units 5 and 6 in June last year. With a project cost of some 407 billion Czech koruna—around KRW 26 trillion—this marks the largest energy investment in Czech history.
In short, the country that once had to import nuclear technology half a century ago is now exporting nuclear plants internationally. Yet, the core issue that first drove Korea to opt for nuclear—dependence on imported energy—has not disappeared. Most required energy still arrives from overseas, little changed from 50 years ago.
93.4% of Energy Is Imported... 50-Year-Old Homework Remains Unsold
According to the Korea Energy Economics Institute’s “2025 Energy Statistics Yearbook,” Korea’s energy import dependence in 2024 stood at 93.4%. Energy imports reached KRW 220.0143 trillion, accounting for about 33.5% of the national budget (KRW 656.6 trillion) in the same year. Of this, fossil fuel imports—including petroleum, coal, and liquefied natural gas (LNG)—totaled KRW 218.3104 trillion, making up 99.2% of all energy imports.
In particular, the Middle East supplies 71.5% of Korea’s crude oil imports, more than 2.5 times the dependence on all other regions combined (28.5%). Every time Middle East instability or rising oil prices drives up global markets, Korea’s domestic energy price and supply-demand balance are inevitably affected.
Nuclear power differs fundamentally from oil or LNG in terms of fuel characteristics. Uranium can generate large amounts of energy from a small amount, with easier transportation and storage. Once a reactor’s fuel is loaded, the plant can operate for about 18 months without refueling, enabling a certain degree of stockpiling. This means nuclear can help buffer Korea from supply shocks caused by international unrest.

There are also new factors not present 50 years ago: chief among them, carbon neutrality. According to the United Nations Economic Commission for Europe (UNECE) lifecycle assessment (LCA), nuclear’s greenhouse gas emissions are just 5.1–6.4gCO₂ per kWh of electricity generated—numbers that include not only plant operation but also fuel procurement and plant construction across the entire lifecycle.
In geographically small Korea, land use is also a crucial consideration. UNECE data show that nuclear’s average land use impact score per kWh is 0.05 (max: 0.07), factoring in the full fuel cycle, not just the facility’s footprint.
While energy security remains as pressing as it was in the 1970s, carbon neutrality is now an additional national goal. On top of this, booming AI data center and semiconductor industry electricity demand has emerged as another variable to manage.
AI & Semiconductor Power Demand... Rethinking the Share of Nuclear Power
Accordingly, the debate over nuclear’s future role is shifting. Whereas the past centered on whether to extend the lifespan of reactors or limit the share of nuclear power, the central issue now is how much power capacity—by energy type—must be secured to meet surging demand.
The confirmed 11th Electricity Basic Plan includes two new large reactors (total 2.8GW) and one SMR (0.7GW). Korea currently operates 26 reactors, with 4 more under construction. The new large reactor sites are set for Yeongdeok in North Gyeongsang Province, while the SMR is planned for Gijang in Busan. The target completion dates are 2037 and 2038 for the large reactors, and 2035 for the SMR.
The next big test comes with the 12th plan. The mix of future power sources for post-2040 Korea—nuclear and renewables—will depend on how fast demand for AI data centers and semiconductors grows, and on how much nuclear and renewable generation is procured to meet it. Particularly since large nuclear plants require a long lead time from planning to commissioning, experts argue that long-term capacity needs must be anticipated in advance.
The nuclear industry, in fact, argues that even more new plants will be required than the 11th plan forecasts. The Korean Nuclear Society estimates that, assuming continued 20-year operation extensions for existing plants and an 85% capacity factor, Korea will need 20 new large reactors and 12 new SMRs to maintain a 35% nuclear share of projected 2050 generation needs (143.6GWy). The scenario calls for an average of 1.67 large reactors to begin construction per year from 2031 to 2042.
If the share were set at 50%, the estimate rises to 34 large reactors and 20 SMRs, with an annual average of 2.83 large reactors breaking ground from 2031 to 2042. These figures are a projection by the Korean Nuclear Society—not an official government plan.
Where Will 50 Years of Spent Fuel Go? Another Challenge of the Nuclear Renaissance
Before expanding nuclear power, there is the unresolved issue of spent fuel that has accumulated over the past 50 years. While commercial nuclear operations have steadily grown since Kori Unit 1 in 1978, Korea still lacks both interim storage and permanent disposal facilities outside reactor sites for spent fuel. Spent fuel remains stored at each reactor site.
Storage capacity is also running out quickly. According to the National Assembly Budget Office, as of the end of 2025, Korea has stored 7,619 spent fuel assemblies at Hanbit, 7,548 at Hanul, and 7,471 at Kori—all from pressurized water reactors. At the Wolsong plant, which uses heavy water reactors, the figure is 526,412 assemblies. The storage facility saturation rates are already at 92.9% at Kori, 84.5% at Hanbit, 84.1% at Wolsong, and 73.5% at Hanul. These sites are projected to reach full capacity in 2030 for Hanbit, 2031 for Hanul, 2032 for Kori, and 2037 for Wolsong.
Although Gyeongju, North Gyeongsang Province, hosts a disposal facility for low- and intermediate-level radioactive waste, spent nuclear fuel and other high-level waste are not covered; no interim or permanent repositories for high-level waste have been sited yet.
The government has only recently begun laying the legal groundwork for site selection, based on the “Special Act on the Management of High-Level Radioactive Waste,” enacted last year. In line with the special law, a High-Level Radioactive Waste Management Committee has been formed under the Prime Minister’s office, with its members finalized in March this year. The process ahead involves identifying candidate sites, accepting applications from local governments, conducting basic and in-depth surveys, and holding local referendums to select the final site.

The timeline is long. The special act stipulates that efforts should be made to begin operating interim storage by 2050 and permanent disposal by 2060. Given that Hanbit’s current facility will reach capacity in 2030, Hanul in 2031, and Kori in 2032, this leaves a significant time gap. The government is thus working to expand on-site dry storage at existing plants to bridge this period until interim storage comes online.
An even greater challenge is the volume of new spent fuel that will accrue. In addition to the spent fuel already generated over the past half-century, future facilities must accommodate spent fuel from the remaining operation of the current fleet and any additional reactors built under the 11th plan or future 12th plan.
The special law also requires that 30-year high-level waste management master plans incorporate current and projected waste generation, storage and disposal strategies, and siting/development plans. How much waste future interim and permanent facilities must handle will ultimately depend on the scale of future nuclear expansion.
This is why the nuclear “renaissance” debate cannot focus solely on how many new plants to build. Any increase in new and extended reactor lifespans results in not only more electricity, but more spent nuclear fuel to manage. For nuclear expansion to be sustainable, Korea must find solutions for handling not only the spent fuel accumulated over the past fifty years, but also new volumes produced over coming decades. Preparing for the “back-end” of the nuclear cycle is now equally as important as planning new construction.
The debate around Korea’s 12th long-term power plan has moved beyond the binary “nuclear vs. renewables” framing. While nuclear offers stable power, CO₂ reduction, and reinforces energy security, it also brings significant challenges related to spent fuel, as well as long construction times and costs. Renewable energy is crucial for reducing emissions, but must be matched by investments in grid and ESS (energy storage system) upgrades. To simultaneously provide large-scale, reliable electricity for AI and semiconductors, cut CO₂, and reduce import dependence, Korea must find an optimal power mix that leverages the strengths of both—aligning with the Nuclear Society’s call to treat nuclear and renewables as “mutually complementary partners.”
Fifty years ago, Korea chose nuclear to weather the oil shock—relying on imported technology. Today, after half a century, it is an exporter of nuclear plants, yet now faces the mounting challenge of how to handle decades of accumulated spent fuel. As the range of options for nuclear power expands, so do the factors that must be weighed.
Hot Picks Today
 "You Want Kids to Wear This?"... Zara Halts Sales of 60,000-Won Halloween Costume After Backlash
- "I Got Hired but Can't Use a Keyboard"... The Challenge Making Gen Z New Hires Sweat [The World is Z-Gold]
- "I Thought It Was the Real Thing"... The Surprising Truth Behind This Common Japanese Food [Delicious Story]
- "Boss, What Is This?" The 2,000 Won 'Pizza-Like Rice Cake' Causes a Sensation at Local Shops [Flavor File X]
If it was oil that first prompted Korea to go nuclear, it is now energy security, carbon neutrality, and AI that are reviving the call for nuclear power. As the need for nuclear expansion comes to the fore once again, Korea’s task for the future is to prepare a medium- to long-term power strategy—not just focusing on new reactor construction, but integrating renewables, strengthening the power grid, and establishing comprehensive solutions for spent nuclear fuel.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.