[Editorial] Sharp Rise in U.S. Long-Term Yields Calls for Review of Corporate and Household Debt Structures
The yield on the 10-year U.S. Treasury bond climbed to as high as 5.304% during intraday trading, surpassing its peak just before the 2007 financial crisis. Despite inflation coming in lower than expected, long-term interest rates have risen. This indicates that even if the Federal Reserve does not raise its benchmark interest rate further, the rates applied to long-term borrowing may not easily fall. This trend is attributed to the U.S. economy being stronger than anticipated, increased government Treasury issuance, and rising capital demand driven by artificial intelligence (AI) investments. Additionally, the prolonged war in the Middle East could keep oil prices and inflation unstable, which may also contribute to sustained high long-term rates.
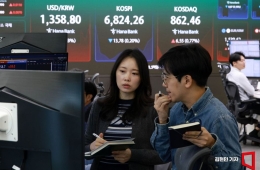
This is not a phenomenon unique to the United States. Long-term government bond yields are also rising in major countries such as Japan, Germany, France, and the United Kingdom. Korea is unlikely to avoid these effects. On September 28, the yield on the three-year government bond soared to 4.119%, and the yield on the 10-year bond jumped to 4.539%. When U.S. rates rise, capital tends to flow into dollar-denominated assets, which can weaken the won and put upward pressure on domestic rates. The government's steps to reduce the issuance of government bonds and, if necessary, to repurchase them are appropriate. However, such measures alone are not sufficient to ease the interest burden on businesses and households.
Companies should review their strategies of relying on short-term bonds based solely on expectations that rates will soon fall. It is necessary to diversify corporate bond maturities and stagger the timing of foreign currency fundraising.
Hot Picks Today
 "Such chaos for the first time in 140 years"... Even illnesses surge, Tokyo stunned by 'unbelievable' event
- "Russia Alarmed by 'Killer Bears'—Not Just a Problem for Japan"
- Furious After Elbow Was Touched While Sleeping, Passenger Threatens to Kick and Forces Flight Attendant to Kneel
- "What Are You Doing Squatting There?"... Picking Up a Few on the Trail Could Result in a Fine
- "Nothing Left to Buy, Feeling Indifferent"... 'Rich Daughter' Vibe in Department Stores with 'Hyunbaek Core'
Financial authorities need to prioritize oversight of companies with debt maturities coming due, starting with those of lower credit profiles who must roll over their loans. Households should also monitor their exposure to floating rates and bullet-repayment loans, and promptly implement measures for vulnerable borrowers. To prepare for the possibility of prolonged high rates, the government, firms, and households all need to preemptively restructure their debt and funding arrangements.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.