Yu Eokwon: "Financial Environment at a Turning Point... Preemptive Response to Unforeseen Risks Needed"
Financial Market Situation Review Meeting Held
Uncertainties Spread by Global Monetary Policy Shifts, AI, Semiconductors, and Middle East Developments
Assessment of Sectoral Potential Risks and Preemptive Preparation of Contingency Measures
Yu Eokwon, Chairman of the Financial Services Commission, has characterized the financial environment—marked by growing internal and external uncertainties such as changes in global monetary policy stance, the outlook for AI and the semiconductor sector, and rising tensions in the Middle East—as a "transition period." He stated that the authorities would take preemptive action against potential risks in each sector. In line with this, the financial authorities plan to monitor refinancing risks, as well as possible deterioration in liquidity and soundness in vulnerable segments. They will also establish a response system in advance so that they can swiftly expand market stabilization programs if market instability increases.

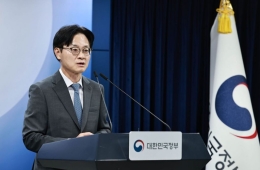
Lee Eokwon, Chairman of the Financial Services Commission, is speaking at the first Emergency Economic Headquarters Meeting and Economic Ministers' Meeting held at the Government Seoul Office in Jongno-gu, Seoul on October 1, 2026. Photo by Jo Yongjun
View original imageOn October 1, the Financial Services Commission announced that it had held a "Financial Market Situation Review Meeting," presided over by Chairman Yu and attended by officials from the Ministry of Economy and Finance, the Financial Supervisory Service, the Korea Institute of Finance, credit rating agencies, securities companies, and other market experts.
During the meeting, participants reviewed the impact of interest rate hikes by central banks in major countries—including South Korea—on the financial market and industry. They also discussed potential risk factors that could increase financial market volatility, such as changes in the AI and semiconductor sectors, global capital flows, and geopolitical risks, as well as strategic approaches to address them.
Chairman Yu stated, "With persistent concerns over global inflation, monetary policy stances around the world are shifting toward tightening. Meanwhile, additional uncertainties—such as changes in the AI and semiconductor sectors and Middle Eastern geopolitics—are accumulating." He assessed the current period as a turning point in the financial environment, explaining, "During such transition periods, risks can emerge unexpectedly from areas past experience cannot predict." He emphasized, "We must thoroughly prepare by examining potential risks across all sectors in advance and from multiple angles, and by getting the necessary response tools ready ahead of time."
Participants reviewed the situation in each sector of the financial market. They noted that while volatility had increased in South Korea’s stock and foreign exchange markets—driven by the war in the Middle East, higher global semiconductor sector volatility, and foreign investors selling Korean stocks—some of these uncertainties have recently eased, and market volatility has somewhat subsided.
In the bond market, domestic government bond yields have risen compared to the start of the year, driven by inflationary concerns due to high oil prices and policy rate hikes in major economies. However, corporate bond spreads have not widened significantly compared to previous crises.
Specifically, the yield on three-year government bonds rose from 2.953% at the end of last year to 3.838% at the end of August this year, and stood at 4.011% as of September 30. Over the same period, the corporate bond spread increased by 16.9 basis points, from 52.3bp to 69.2bp, but this remains well below the peak of 177.2bp seen during the 2022 liquidity crunch.
Attendees expressed consensus that the market stabilization program, which has actively purchased corporate bonds and commercial paper totaling 12.1 trillion won since the outbreak of the Middle East war in March, has functioned as a buffer mitigating shocks in the bond market. They also agreed that Korea’s economy and financial system are well-positioned to withstand crises and absorb shocks, given resilient exports and growth, the financial sector's soundness, and strong external stability indicators, even in the face of high internal and external uncertainty.
However, participants voiced concern that the gradual rise in market interest rates is increasing the funding cost burden for market participants and raising market sensitivity to rate changes. In particular, they cautioned that if unexpected domestic or external credit events occur, refinancing conditions could rapidly deteriorate, causing refinancing risks in vulnerable sectors to quickly spill over into the broader market and impact the overall soundness of the financial sector.
Additionally, they highlighted the need for continuous monitoring of major risk factors, including liquidity risks stemming from mismatched maturities between funding and investment, a concentration of funds in specific sectors, the clustering of bond issuance and maturity at certain times, increased repayment burdens for vulnerable borrowers, and uncertainty regarding the outlook for AI and the semiconductor markets.
Chairman Yu called for a thorough and multi-faceted review of market risk factors, including extreme tail risks and their possible transmission channels. He stressed the importance of implementing sector-specific market stabilization measures (Contingency Plans) promptly if market instability spreads.
He specifically directed that, as the upward trend in market interest rates continues, authorities should actively deploy market stabilization programs to ensure the stability of the bond and money markets. He also instructed that preparations should be made in advance to swiftly expand support if bond market volatility increases excessively.
Furthermore, he called for a proactive review of the issuance volume and maturity structure of bank bonds, credit-specialized company bonds, and other instruments in the fourth quarter, in order to prevent market supply-demand imbalances arising from concentrated bond issuance during specific periods. He also emphasized the need for careful monitoring of the asset quality, liquidity, and funding structures of the financial sector during periods of rising interest rates.
Hot Picks Today
 "From 20s to 60s, Everyone Rushed In"...The 'Top License' Also Obtained by Actors Yoo Yeon-seok and Sung Hoon Revealed
- "Unbelievable Event" in Tokyo Leaves Japan Stunned...Even 'Weather-Related Illnesses' Emerge
- Smoking Cigarettes and Taking Photos at Gyeongbokgung Palace..."I Don't Know How to Smoke," Foreign Tourists Deny Accusations
- "The Real Winner Controls the Heat"...LG Electronics Bets 150 Billion Won on New Chiller Plant in Virginia, US
- The Effortlessly Chic "Rich Daughter" Mood... Have You Heard of the Latest Trend, "Hyunbaekcore"?
He instructed that support measures for vulnerable borrowers in preparation for further rate hikes should proceed without delay. He also called for close monitoring of lending rate trends and the potential for increased repayment burdens by sector, with timely supplementary measures to be taken if necessary.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.