[Exclusive] 400 Billion Won in Loans Collected from Multi-Homeowners in 4 Months After New Regulations... 6% of Matured Loans in Delinquency
Performance Review Through August After April 1 Regulations
37.7% of Matured Loans Collected... 600 Billion Won Rolled Over
6% of Matured Loans in Delinquency... Listing Surge Marginal
"Comprehensive Multi-Homeowner Crackdown Only Fue

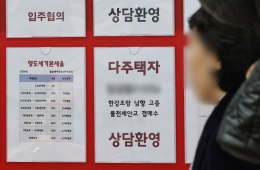
Just four months after the 'April 1 Real Estate Measures' tightened loan regulations for owners of multiple homes, over 400 billion won worth of mortgage loans have been recalled. Even though there were a significant number of exceptions, the fact that 38% of maturing loans were called in indicates that the government policy was implemented at a rapid pace.
However, 6% of maturing loans have either failed to repay principal or become delinquent due to overdue interest payments. The anticipated effect—encouraging owners of multiple homes to release more properties onto the market—has also not materialized clearly. Since wide-ranging regulations on owners of multiple properties, including lending and tax rules, have reduced the supply of rental properties, potentially destabilizing the rental market, there are calls for a thorough review of the policy’s effectiveness.
After the ‘Principled Ban’ on Mortgage Loan Extensions for Owners of Multiple Homes... 420 Billion Won in Loans Recalled

According to data obtained on September 30 by Assemblyman Park Sung-hoon of the People Power Party, a member of the National Assembly’s Political Affairs Committee, from the Financial Supervisory Service, a total of 422.29 billion won (3,472 cases) worth of mortgage loans for multiple home owners was recalled between April 17—when loan extensions were in principle banned—and the end of August. During this period, 1.1176 trillion won (6,029 cases) in mortgage loans matured, and 37.7% of the total amount was repaid.
The government, through its April 1 real estate policy, prohibited mortgage loan extensions for apartments owned by multiple home owners in the Seoul metropolitan area and regulated zones, and initiated measures for calling in existing loans. The policy aimed to sever the link between real estate and finance and to induce owners of multiple homes to put their properties on the market, thereby stabilizing home prices. Yet, considering the potential impact on the rental market, exceptions were permitted for cases where there were tenants, the owner was a registered rental housing provider, or where public interest purposes were recognized. As a result, 37% (2,217 cases) of mortgage loans maturing in this period were extended. In terms of amount, this represented 628.43 billion won, or about 56% of the total amount maturing.
The financial sector has assessed the pace of loan recalls as faster than expected. A banking industry representative stated, "Typically, mortgage borrowers expect that unless they sell their home, it would be possible to extend or refinance their loan; so they have managed funds accordingly. Given this sudden policy shift, having over 400 billion won recalled is not a small figure."
6% Delinquency Rate on Maturing Debt Due to Repayment Pressures... Concerns Over Added Burden Amid Transaction Slump and Rate Hikes
There were also not a few cases where borrowers fell into delinquency due to the inability to bear the repayment burden. From April 17, when the regulation took effect, until the end of August, a total of 340 cases (66.85 billion won) became delinquent. This equates to 6% of the total maturing loans over the period. This includes cases where the borrower was unable to repay the principal after loan extension was denied, as well as those where the loan was extended but the borrower failed to pay interest. The Financial Supervisory Service commented, "In most cases, delinquencies arose because extensions were not granted."
Banking circles note that although the current scale of delinquency is not large, given these are loans secured by residential property, the risk of wider financial instability remains low; however, the 6% delinquency rate relative to maturing loans is still significant. While it is difficult to directly compare this to the typical delinquency rate, which is calculated against the total outstanding balance, as of the end of June, the overall household loan delinquency rate at domestic banks stood at 0.40%, with the mortgage delinquency rate at 0.28%.
Especially with the apartment sales market stagnating in Seoul and as interest rates continue to rise, extending these policies could lead to more delinquencies. Hyosun Kim, Senior Real Estate Specialist at KB Kookmin Bank, observed, "If it's a popular apartment, liquidity would flow smoothly, but if it's not in a prime area, even if you list it, it may not sell, creating difficulties in repaying the loan. For borrowers who want to repay but can't, it's an extremely harsh situation as they have to risk their personal credit rating."
Little Evidence of a Surge in Listings... Criticism That Comprehensive Regulations Only Add to Rental Market Instability

The anticipated effect of bringing more properties held by multiple-home owners to the market through stricter loan regulations appears to be weaker than expected. According to Asil, a real estate big data firm, the number of apartment listings in Seoul decreased from 75,650 on April 17 to 66,808 at the end of August—a drop of 8,842. In the 'Gangnam 3 districts'—Gangnam, Seocho, and Songpa—with high outstanding multiple-home owner loan balances, listings rose by only 48, from 25,609 to 25,657 over the same period.
Market analysts believe that the increase in listings in the Gangnam 3 districts was likely affected more by temporary relaxations or anticipated tightening of tax regulations than by loan regulations for multiple-home owners. In fact, in Gangnam-gu in Seoul, listings increased in April to early May and again from mid-August, which coincided with the announcements of policies such as the temporary easing of transfer income tax surcharges and measures related to the comprehensive real estate tax (so-called 'comprehensive tax'), reflecting adjustments in tax policy at the time.
There are also concerns that wide-ranging regulations on loans and taxes for owners of multiple homes may have actually intensified instability in the monthly and yearly rental markets, potentially fueling further increases in home prices. Yang Ji-young, Expert Consultant at Shinhan Premier Pathfinder, stated, "What's more important than the amount of loan recalled from multiple-home owners is whether there was a real boost in listings. Loan restrictions may gradually normalize leverage structures for such owners, but a series of wide-ranging regulations have, in fact, heightened rental market instability and produced adverse side effects in the real estate market."
Hot Picks Today
 "Falling Asleep Instantly in Bed"...Is a Nightly Pattern a Warning Sign for Your Health?
- Where Have All the 'Finished Today's Workout' MZs Gone?... 6 Out of 10 Men in Their 30s Are Obese
- Yoo Haejin Called "North Korean Face," "Who Pushed Roh Moo-hyun?"... People Power Party Launches Fierce Attack on Assassin(s)
- Cracked Underground Parking Lot... Residents Protest: "4-Meter Giant Piles Damage Apartment Foundation"
Assemblyman Park Sung-hoon commented, "I question whether the Lee Jaemyung administration’s artificial measures targeting owners of multiple homes are actually stabilizing the real estate market, or only compounding borrower distress and financial market instability. We need to thoroughly reassess and review loan regulation policies starting from square one, taking into account both their effects and side effects."
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.