BOK: 1 in 5 Companies Unable to Cover Interest with Earnings... Strengthened Soundness Management Needed [Financial Stability Report]
Bank of Korea Releases Financial Stability Report (September 2026)
46.3% of Vulnerable Companies Have an Interest Coverage Ratio Below 1
High Proportion of Marginal Companies in Domestic Sectors Such as Real Estate and Hospitality
Corporate Interest Burden Rises by 3.7 Trillion Won for Every 0.25%P Hike in Benchmark Rate
It has been revealed that the proportion of marginal companies, which are unable to cover interest expenses with operating profits, reached one-fifth of all companies last year.
According to the Financial Stability Report for September 2026 announced by the Bank of Korea on September 22, as of the end of last year, marginal companies accounted for 19.1% of all externally audited companies, a 2.0 percentage point increase compared to the previous year. Marginal companies are defined as those whose interest coverage ratio stays below 1 for three consecutive years.
Out of the total 29,468 non-financial externally audited corporations, 5,632 qualified as marginal companies. Notably, 66.6% of last year's marginal companies remained in that category for two consecutive years, indicating the difficulty of escaping the marginal status.
As of the end of the first quarter of this year, the proportion of vulnerable companies with an interest coverage ratio of less than 1 was calculated at 46.3%. By company size, the share of marginal companies among small and medium-sized enterprises (SMEs) increased from 18.0% in 2024 to 20.0% last year, and among large companies from 13.7% to 15.5% over the same period.
By industry, sectors serving domestic demand such as real estate (43.7%) and hospitality·food services (28.4%) showed high proportions of marginal companies. In real estate, the rate rose by 4.3 percentage points compared to 2024, and increases were also seen in metal products (from 8.0% to 11.6%), construction (11.7% to 12.1%), petrochemicals (11.1% to 12.8%), and wholesale & retail (10.7% to 13.4%).
Despite strong performance in the semiconductor sector, the proportion of marginal companies in the electrical·electronics sector also rose by 2.5 percentage points, from 15.4% to 17.9%.
The proportion of bank credit extended to marginal companies as a share of total corporate lending increased from 15.6% in 2024 to 21.2% last year. By company size, the figure for SMEs rose from 19.2% to 28.9%, a larger increase compared to large companies (from 14.0% to 18.2%).
By type of financial institution, the increase was more pronounced in the non-bank sector. The proportion of bank lending to marginal companies rose from 15.1% to 18.4%, while the share for non-bank institutions increased from 16.6% to 27.0%.
The share of total financial institution credit to marginal companies provided by non-bank institutions also expanded from 38.2% to 42.2%. In the petrochemicals sector, the proportion of marginal companies by credit soared from 14.0% to 36.1%. This was due in part to the inclusion of major large companies with large-scale loans as marginal companies, as a result of continued structural weaknesses such as global oversupply.
The proportion of cash and cash equivalents to total assets for marginal companies stood at 6.6% at the end of last year, lower than for non-marginal companies (11.0%). The current ratio, calculated as current assets divided by current liabilities, was 77.2%, falling short of 100%.
Jungsoo Jang, Deputy Governor of the Bank of Korea, stated, "The increase in the proportion of vulnerable borrowers, rising share of loans with variable interest rates, and higher delinquency rates all indicate that interest rate increases will pose a greater burden to vulnerable companies than to the household sector."
Gwanggyu Lim, Head of the Financial Stability Department at the Bank of Korea, added, "If the benchmark interest rate rises by 0.25 percentage points, the interest burden would increase by approximately 3.3 trillion won for households and about 3.7 trillion won for companies."
However, based on various indicators, the proportion of high-risk companies among marginal companies, as estimated by the authorities, declined for the second consecutive year to 38% last year, and the share of high-risk company loans among marginal company loans also fell to 26.1%. This was due to higher capital adequacy ratios and an increase in interest coverage ratios, showing a partial improvement in profitability concerns.
Hot Picks Today
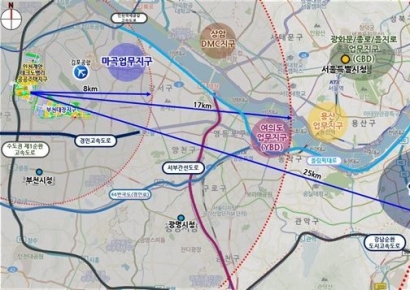 "Why Live in Seoul When You Can Pay Half Here?" 30 Minutes to Gangnam... Private Sales Begin in Gyeyang New Town
- "Living Becomes Easier Thanks to SK Hynix, But Conservative U.S. Cities Remain Torn Inside [U.S. Midterm Election D-40]②-2"
- "I Went for the Cheap Coffee, but Now I Feel Uneasy"... Major Coffee Franchises Cited for Violations One After Another
- "Once You've Been Here, It's Hard to Leave"... 9 Out of 10 Foreigners in Korea Say They Want to Stay
- "After Spending 170,000 Won on Hanwoo, This Is What I Got": Why Webtoon Artist Kim Gyusam Decided to Give Cash Instead
The Bank of Korea emphasized, "Because vulnerability may increase in sectors with sluggish business conditions, we must strengthen loan monitoring and maintain soundness management, with particular attention paid to increased interest burdens from rising market interest rates and the greater refinancing risks faced by companies with high reliance on market-based funding."

© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.