"The Dawn of Domestic Inference... Time to Bet on NAVER" [Click eStock]
On September 22, Meritz Securities maintained its target price for NAVER at KRW 330,000 and its "Buy" investment opinion, stating that concerns about the existing businesses have already been sufficiently reflected in the share price, while visibility into sales from the new "Neo Cloud" business is becoming clearer.

Hyojin Lee, a researcher at Meritz Securities, wrote in a report on this day, "Since NAVER announced its entry into the artificial intelligence (AI) factory business in June, concrete details have been made public, including participation in Nvidia's USD 1 billion paid-in capital increase. However, as actual revenue is expected to materialize only next year, NAVER is entering a momentum gap, and the uncertain returns on capital allocation have led to investor disappointment."
Regarding NAVER's recent shift to focus on short-term contracts ranging from six months to two years, Lee commented, "A short-term contract strategy targeting a broad customer base, similar to global AI infrastructure companies like Nebius and CoreWeave, reflects an industry trend of supplier-dominated markets. With the B300 Rubin-based GPUaaS, NAVER may be able to command a unit price of more than KRW 30 billion per MW."
Hot Picks Today
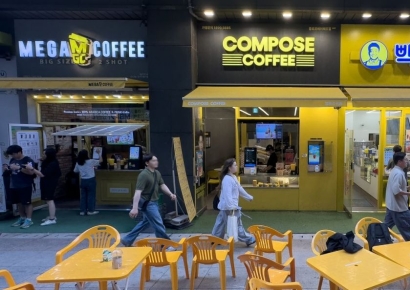 "I Went for the Cheap Coffee, but Now I Feel Uneasy"... Major Coffee Franchises Cited for Violations One After Another
- In Korea, Studying Medicine Is in High Demand, but in China, It's Shunned: "Why Become a Doctor When You Can’t Make Money?"
- "Surprisingly Real, Perfect Like AI" -- Global Media Praise Korean Fencer's Beauty
- "50 Million Won for Weekly Encounters"... Man in His 60s Sentenced for Deceiving Woman in Her 20s with Forged 1.4 Billion Won Account
- "I've Already Booked My Trip to Japan, But This Is Serious"...Highest Number of Measles Cases in Japan in a Decade Spurs Emergency Alert
The decisive catalyst to alleviate market concerns is expected to materialize starting in October. Lee noted, "Around the time of Nvidia's paid-in capital increase payment date, GPU shipments and announcements of new order contracts are likely to become more concrete. The customer base may also expand beyond Anthropic and OpenAI to include global cloud service providers (CSPs) in need of domestic inference infrastructure."
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.