"With 'SamjeonNix' Concentration Easing, It’s Time for Small and Mid-Cap Stocks"
As the concentration on “SamjeonNix” in the domestic stock market eases, an analysis has emerged suggesting that small and mid-cap stocks will attract more attention.

According to independent research firm Growth Research, a recent industry report analyzed both the relative appeal and re-rating factors for small and mid-cap stocks, noting that the stock market’s heavy focus on Samsung Electronics and SK hynix is now subsiding.
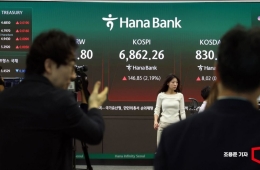
The report states that, in the first half of this year, Samsung Electronics and SK hynix accounted for 78.3% of the KOSPI’s gains. The surge in memory prices has driven earnings growth for both companies, but the pace of price increases has slowed since the second half of the year. Growth Research pointed out that, as the memory sector transitions from price-driven to volume-driven growth, the relative attractiveness of small and mid-cap stocks—previously overlooked—may come into sharper focus.
Small and mid-cap stock earnings are improving as well. Operating profits among KOSDAQ-listed companies in the first half of this year rose by 62.2% compared to the same period last year. After the concentration in BBIG stocks in 2020, large-cap stocks fell by about 1% in 2021, but mid-cap and small-cap stocks increased by approximately 9% and 15%, respectively. This analysis suggests that it is important to select companies that have been neglected in terms of supply and demand, especially as profit growth continues and valuations remain low, rather than simply seeking stocks that have dropped in price.
Based on criteria such as profit growth, undervaluation, and being overlooked by mainstream flows, the report picked Daejoo Electronic Materials, Sunjin, and MegastudyEdu as noteworthy companies. Daejoo Electronic Materials is expected to benefit from expanding supply of silver paste as well as simultaneous growth in conductive paste for MLCC and silicon anode materials. As of the first half of this year, Sunjin’s cash holdings—including cash equivalents and short-term financial assets—stood at 273.8 billion won, exceeding its market capitalization. For MegastudyEdu, the expected dividend yield as of closing on September 18 was 9.4%.
Hot Picks Today
 Why Didn't My Loan Interest Rate Drop Even After Regular Salary Transfers?… FSS Says "Check This"
- "Is the YouTuber Telling the Truth?" 300,000 Views in One Day... The Real Story Behind Shin Ramyun's Flavor, According to Nongshim [Tastelovers X-File]
- "With 'SamjeonNix' Concentration Easing, It’s Time for Small and Mid-Cap Stocks"
- "I Can't Believe There Are Such Kids These Days"... Middle School Students Help Elderly Man Collecting Scrap Paper All the Way to Junk Dealer
- "They Might Start Pitching Tents and Grilling Meat"... The 'Hammock Villain' Appears at Cheonggyecheon
Yonghee Han, a researcher at Growth Research, stated, “Rather than a slowdown in profit growth across the memory sector, it is important to focus on the narrowing gap of profit growth that had been concentrated in Samsung Electronics and SK hynix,” adding, “Going forward, it is crucial to select small and mid-cap stocks with both profit growth and undervaluation that have not been fully reflected in share prices due to supply and demand concentration, despite improving earnings.”
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.