'50%+1 Share' Mandatory Tender Offer System Passes Political Affairs Committee... Criticism It Undermines President’s Pledge
Bipartisan Compromise Reached on “50%+1 Share” Instead of “100% Tender Offer”
Governance Forum Criticizes It as “Not a Half Measure, But a Bad System”
The mandatory tender offer system, which allows minority shareholders to sell their shares at the same price as the former largest shareholder when the management rights of a listed company change, has passed the National Assembly’s standing committee. However, the scope of the tender offer was set using the "50%+1 share" method, rather than encompassing all remaining shares, leading to criticism that this undermines President Lee Jaemyung’s original campaign pledge to protect minority shareholders.
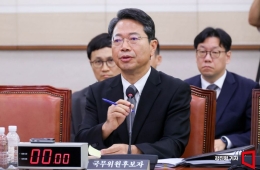
The National Assembly’s Political Affairs Committee held a plenary session on the 17th and passed the amendment to the Capital Markets Act reflecting these changes. According to the amendment, a mandatory tender offer will be applied when someone acquires 25% or more of shares in a listed company to become the largest shareholder, as well as when an existing largest shareholder holding 25% or more of the shares buys additional shares. The scope of the tender offer is up to 50%+1 share of the total issued shares, including the shares already owned. If subscription falls short of the target, only the tendered shares need to be purchased.
The introduction of the mandatory tender offer system accelerated after Chilseung Kwon, policy chief for the Democratic Party, and Lee Ija, policy chief for the People Power Party, reached an agreement at the National Policy Roundtable on the 15th to adopt the “50%+1 share” standard. This represents a compromise, stepping back from the Democratic Party’s earlier call for a “100% tender offer.” After passing the standing committee, the amendment now awaits deliberation by the Legislation and Judiciary Committee and a final vote in the plenary session. There is a possibility that the system will be implemented within this year.
If the system is adopted, there will inevitably be repercussions in the listed company M&A market. In the private equity fund (PEF) sector, there are forecasts that takeover premiums for management rights in listed companies will be reduced, or that there will be greater preference for acquiring unlisted companies, given the additional costs imposed by the tender offer requirement. Assemblyman Jo Jeonghun of the People Power Party abstained in the vote, commenting that “More capital will be required to defend management rights than before,” and added, “Only global funds with huge capital, rather than relatively small domestic private equity funds, will be able to participate in domestic M&As.”
On the other hand, there are also strong criticisms that the scope of the tender offer must cover all remaining shares in order to uphold the system’s original purpose of protecting minority shareholders. Assemblyman Han Changmin of the Social Democratic Party argued, “It is desirable to require the acquisition of all remaining shares through the tender offer,” and added, “If limited to 50%+1 share, existing controlling shareholders can continue to enjoy a control premium, but it is difficult for all minority shareholders to enjoy the same benefit.”
The Korea Corporate Governance Forum also issued a strongly-worded statement on this day entitled, “‘50%+1 share’ partial mandatory tender offer is not a ‘half measure’ but a ‘bad system’,” declaring: “At the very least, controlling shareholders should be allowed to sell only through the tender offer (pro-rata purchase). If even that is not possible, then it’s better to not legislate at all.”
The Governance Forum pointed out, “The President’s pledge was to provide for ‘sharing control premiums’ and ‘ensuring exit opportunities for minority shareholders,’ but the ‘50%+1 share’ amendment fails to accomplish either. For minority shareholders of companies where controlling shareholders already own a majority, there is no protection. It also converges the controlling shareholders’ ratio across the market to ‘50%+1 share,’ worsening the overall governance environment.”
Comparing to overseas precedents, the UK, European Union (EU), Hong Kong, and Singapore all require tender offers for acquiring control to cover all outstanding shares. In Japan, where a tender offer may exceed two-thirds, there are multiple safeguards, such as prohibiting separate purchases during the tender period and mandating that, if oversubscribed, even major shareholders must participate on a pro-rata basis without exception, making such protection robust.
Hot Picks Today
 "Inside, It's a Shock... A Daughter Born in the 1990s Ages Faster Than Her Mother Born in 1965"
- "Plenty of Holiday Expenses, but Even Fewer Companies Are Paying Bonuses This Year"
- "Three Days Off in a Row Is Sweet?" Four-Day Workweek Begins, but Unexpected Burnout Emerges
- Man in His 30s From 'Suwon Drug Video' Admits to Using Methamphetamine Abroad
- "Is It Really a Healthy Oil?"... The Surprising Risks of Frying Eggs with Coconut Oil
Therefore, the Forum argues that if the “50%+1 share” amendment is enacted, two supplementary measures must be implemented. The Governance Forum asserts, “Controlling shareholders should only be allowed to sell via a tender offer. In Japan, acquisitions exceeding 30% are conducted through a tender offer, and even major shareholders are included on a pro-rata basis. If partial tender offers must be introduced, approval should be required from a majority of independent shareholders, excluding the acquirer, selling controlling shareholders, and special affiliates, and dissenting shareholders should also be able to tender their shares on the same terms after the offer goes through.”
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.