NICE Credit Rating: Securities Industry Faces Test of Profit Sustainability Amid Market Boom
Profit and Loss Sensitive to Stock Market Conditions Up by 10 Percentage Points YoY
Widening Gap Between Large and Small-to-Mid-Sized Firms
Competition Intensifies in IMA and Promissory Notes
NICE Credit Rating analyzed that while securities firms enjoyed record-breaking results during this year's stock market boom, the gap between large firms and small- to mid-sized firms has widened. The company noted that as profits have risen in sectors highly dependent on favorable stock market conditions, there is a need to assess the long-term sustainability of this performance.
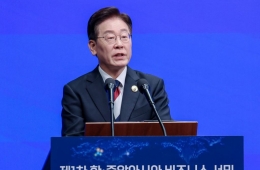
Seunghwan Shin, Senior Researcher at NICE Credit Rating, said at the "NICE Credit Seminar 2026" held at the Korea Exchange on September 16th, "The consolidated net profit of the domestic securities industry in the first half of the year reached 8.9 trillion won, the highest ever for a half-year period. Retail businesses led performance improvement, with commission brokerage revenue increasing by 5.3 trillion won, financial revenue by 1.4 trillion won, and asset management revenue by 1 trillion won compared to last year."

Shin Seunghwan, Senior Researcher at NICE Credit Rating, is answering questions at the 'NICE Credit Seminar 2026' held at the Korea Exchange on the 16th. Photo by Kim Youngwon
View original imageIn particular, the share of profit and loss highly sensitive to stock market conditions—such as commission brokerage, asset management (wealth management), and margin lending interest income—increased to 61% at large firms and 56% at small and mid-sized firms. This represents a more than 10 percentage point increase from 51% and 42%, respectively, a year ago.
Even amidst record results, polarization by firm size within the securities industry has intensified. The ROA (Return on Assets) in the first half of the year was 1.8% for large firms and 1.1% for small and mid-sized firms, with the gap widening compared to the 0.5 percentage point difference in the first half of last year.
Even in the recovery trend of real estate finance, the gap between large firms and small- to mid-sized firms expanded. As of the end of June this year, exposure to real estate PF (project finance) stood at around 55 trillion won, down 1.2% compared to the end of the previous year, but the recovery pattern has diverged since the Legoland incident of 2022. Shin explained, "Large firms are increasing their exposure, while small and mid-sized firms are taking a more conservative approach, as the disposal of distressed assets continues to take longer."
Furthermore, changes in the PF (project finance) market also acted as one axis of polarization. Shin said, "In the past, abundant liquidity and active sell-downs provided small- and mid-sized firms with room to operate, but with rising construction costs and stricter business viability assessments due to high interest rates, funding is now concentrating on large, premium projects where demand is evident. As a result, business opportunities are increasingly focused on firms with capital strength and high credibility, exacerbating polarization."
The intensification of capital competition in the securities industry as a result of the market boom is also identified as a structural shift. Unlike banks or other financial industries, where increased capital is typically used to limit leverage and risk, the securities industry has unique characteristics whereby regulations provide incentives based on capital scale, due to policy objectives. Shin noted, "While other financial sectors raise capital during periods of poor performance to defend regulatory ratios, securities firms tend to expand capital during periods of improved performance."
From this perspective, the expansion of IMA (Investment Management Account) authorizations and issued promissory notes has also accelerated industry competition. Shin pointed out, "While such capital expansion is positive in terms of enhancing a firm's ability to absorb losses, there are factors that encourage companies which have recently raised capital to take on greater risk in order to boost returns, and competitors to increase risk-taking to narrow the gap. It is therefore necessary to monitor both how expanded capital is allocated and how competitive dynamics are affecting risk appetite."
Shin also analyzed whether the securities industry's strong profits can be sustained after this boom period. He first pointed to the risk that daily trading value may not rebound to previous peaks. Last month, the average daily trading value had decreased by 33% compared to its peak in June. Citing previous boom-bust cycles such as the dot-com bubble (2000) and COVID-19 (2021), Shin said, "Stock prices and trading value do not necessarily recover in tandem, and once trading value decreases, it can take time for the trend to recover. Assuming that June 2024 marks the peak, and applying the pattern observed in 2021, transaction volume in the second half is likely to fall by about 16% compared to the first half."
He added, "Revenue that increased in the second half could shrink quickly, but expanded cost structures and risk exposure are difficult to reduce in a short period of time. This difference in speed can heighten downward pressure on profitability."
With regard to the interest rate environment, Shin predicted that market rates, rather than benchmark rates, will have a greater impact. He stated, "Over the past decade, movements in bond portfolio returns have depended more on how much and how quickly market rates have moved, rather than on policy rate hikes themselves. Losses tended to be concentrated during periods when spreads between government bond yields and benchmark rates widened. This same trend has persisted from the second half of last year through the first half of this year."
He particularly assessed that such interest rate burdens are spilling over from bond portfolio losses to the overall soundness of corporate finance. As of the end of June, credit exposure in the securities sector stood at around 90 trillion won. Shin explained, "While banks focus primarily on a company's ability to repay when supplying funds, securities firms place greater emphasis on transaction structure and exit strategies, since they are more centered on such deals as acquisition finance and project finance. A contracted recovery market due to rising interest rates could lead to longer holding periods."
Shin highlighted the need for long-term performance verification for the expansion of IMAs and issued promissory notes. "Since these assets have longer recovery periods, investment results need to be judged over time. Looking at venture capital as an example, realized income depends greatly on IPOs. If listing conditions worsen, delayed recovery and lower profitability should be expected," he said.
Hot Picks Today
 "They Really Might Take No.1"... Nongshim Narrows Gap with Japan from 9.2% to 1.9% in a Year, Closing In on Market Leader
- Jensen Huang Reacts to Douzhi; HYROX Female Champion Faces Ordeal Mid-Race: Was a 'Chinese Drink' to Blame?
- Japanese "Short Sleeper" Who Claimed to Be Fine on 30 Minutes of Sleep a Day Caught Napping During Live Broadcast
- "Please Take Off Your Shoes"—From Crawling onto the Bed to Changing Habits, Young Americans Lead the Shift
- "The Clothes My Dad Used to Wear"... Ralph Lauren, Beanpole, and Hazzys See Sales Surge as MZ Generation Embraces the Trend
NICE Credit Rating assessed that overall, the credit outlook for the securities industry is stable for both large and small- to mid-sized firms. However, for small- and mid-sized firms, there is uncertainty regarding the structural sustainability of the recent improvement in results, and firms with pronounced weakness in core operations or declining competitive positions may face heightened downward pressure.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.