[Exclusive] Regional Main Streets Freeze Despite Semiconductor Boom... Delinquency Rate for Self-Employed at Regional Banks Surpasses 1%
Regional Self-Employed Loan Delinquency Rate Hits 1.04%... Tripled in Three and a Half Years
Widening Gap with Top Five Banks as Regional Economies Suffer Direct Impact
High Interest Rates and Oil Prices... "Concerns Rise Over Expanding Defa
The delinquency rate on loans to individual business owners at regional banks exceeded 1% in the first half of this year. While Korea's economy is experiencing rapid growth, led by flagship export industries such as semiconductors, the benefits of the recovery have not been evenly distributed to regional economies and the domestic market. As a result, the debt repayment capacity of regional self-employed people has shown little improvement. Concerns are rising that, with the added pressures of rising international oil prices and inflation, the yield on 10-year U.S. Treasury bonds has surpassed 5% for the first time in three years, leading to upward pressure on market interest rates. This raises fears that loan delinquencies could further expand, particularly among vulnerable regional self-employed borrowers.
Regional Banks’ Delinquency Rate at 1.04%... Twice That of the Five Major Banks

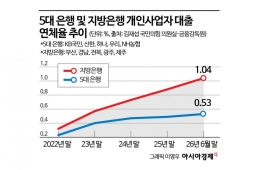
According to data submitted by Assemblyman Kim Jaesub of the People Power Party, a member of the National Assembly’s Political Affairs Committee, and obtained from the Financial Supervisory Service on September 15, the delinquency rate on loans to individual business owners at Busan Bank, BNK Kyongnam Bank, Jeonbuk Bank, Kwangju Bank, and Jeju Bank stood at 1.04% at the end of June. This rate has been steadily climbing: from 0.32% at the end of 2022 to 0.57% at the end of 2023, 0.73% at the end of 2024, and 0.88% at the end of last year—ultimately surpassing 1% in the first half of this year. In just three and a half years, the rate has more than tripled.
The upward trend is also evident among the five major commercial banks (KB Kookmin Bank, Shinhan Bank, Hana Bank, Woori Bank, and NH Nonghyup Bank), but the pace is slower than at regional banks. Their delinquency rates on loans to individual business owners rose from 0.23% at the end of 2022 to 0.40% at the end of 2023, 0.47% at the end of 2024, 0.49% at the end of last year, and climbed to 0.53% at the end of June. As a result, the gap between regional banks and the five major banks widened from 0.09 percentage points at the end of 2022 to 0.51 percentage points at the end of June. The delinquency rate at regional banks is now nearly twice that of the five largest banks.
The overall delinquency rate on loans to individual business owners at all domestic banks also more than doubled, rising from 0.26% at the end of 2022 to 0.69% at the end of June.

Semiconductor Sector Thrives, But No "Trickle-Down Effect" for Regional Economies
The particularly rapid increase in regional bank delinquency rates is rooted in the sluggish recovery of local economies. In the first half of this year, Korea’s real GDP grew 3.8% year-on-year, but the growth was driven by a few major export companies such as those in semiconductors. There is a stark gap between these headline figures and the economic realities felt by small and medium-sized enterprises (SMEs) and self-employed individuals. Especially in regions where industrial infrastructure has weakened, a large share of SMEs, declining consumption, and a sluggish construction sector mean that local players are unable to benefit from the export boom’s trickle-down effect.
A source at a regional bank said, “The improved performance of export conglomerates feels like a distant story. There is no money circulating in the region, business foundations are rapidly weakening, and bad debts are worsening.”
The weakness of regional economies is directly impacting the soundness of regional banks. As of the end of June, the ratio of non-performing loans (NPLs) delinquent for over three months stood at 1.50% at Jeju Bank, 1.34% at Jeonbuk Bank, 1.10% at Busan Bank, 1.09% at BNK Kyongnam Bank, and 1.01% at Kwangju Bank, with all five exceeding 1%. This is significantly higher than the domestic banking sector’s average of 0.63%.
Profitability is also worsening for small business owners. According to Korea Credit Data (KCD), profit margins of small businesses fell year-on-year in 8 out of 16 cities and provinces nationwide in the second quarter. Among the key business regions for regional banks, profit margins dropped by 2.13 percentage points in Jeju, 1.23 percentage points in Gyeongnam, and 0.30 percentage points in Gwangju. The amount of delinquent loans to individual business owners—adding both bank and non-bank financial institutions—reached 15.2 trillion won, up 4.3% from the previous quarter.

High Interest Rates and Oil Prices Raise Red Flags for Self-Employed Borrowers
Going forward, high interest rates and high oil prices are expected to put further pressure on regional self-employed business owners. With the yield on 10-year U.S. Treasuries breaking above 5% and international oil prices topping $100 per barrel again, self-employed individuals are simultaneously shouldering increased interest expenses as well as higher raw material and logistics costs. If financial burdens and cost pressures grow at a time when sales are recovering only slowly, the repayment ability of these businesses will further deteriorate—and this could accelerate the transmission of self-employed loan defaults into a deterioration of regional banks’ asset quality.
Hot Picks Today
 "Bought Raw Materials at 1,500 Won, Selling at 1,300 Won"—Exchange Rate Plunge Casts a Shadow as Export Giants Face Third-Quarter Alarm
- "An Insult to All Women": Female Athletes Outraged Over Ad with 37 Million Views in Four Days
- Police Give 70,000 Won of Their Own Money to Homeless Man in His 40s Who Stole Two Bags of Potato Rice Cakes Out of Hunger
- "This Is a Must-See"...Tourism Industry in Japan Hits 4-Trillion-Won Jackpot
- "Weight Dropped Rapidly... Anyone Can Get It Easily": Why a Woman in Her 20s Quit Mountzaro After Losing 6kg in a Month
Kim Jeongsik, Professor Emeritus of Economics at Yonsei University, commented, “Even if certain sectors such as semiconductors rebound, the ripple effect on domestic demand is limited, leading to a K-shaped polarization. If high interest rates continue and the domestic economy further weakens, the delinquency rate on loans to individual business owners at regional banks could rise even higher. The government should consider initiatives to revive the construction sector and boost domestic demand in order to revitalize regional economies.”
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.