[Exclusive] Financial Regulatory Sandbox Reduced to Complaint Desk for Traditional Institutions [Innovationless Innovative Finance]②
Using the 'Innovative Financial Service' Route Instead of Regulatory Amendments
More Than Half of All Designations Involve Network Separation for Financial Institutions
Less Than 3% of Designations Are Related to Blockchain
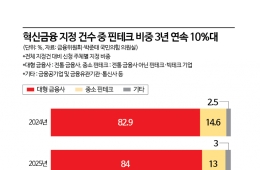
A comprehensive review of cases designated under the financial regulatory sandbox, which began in 2019, has revealed that more than half of the cases address the "complaints" of traditional financial institutions. Critics point out that even though regulations could be relaxed through the revision of notifications or rules, these institutions use the sandbox to resolve complaints instead.
According to data titled "Status of the Financial Regulatory Sandbox" obtained by Representative Park Joon-tae of the People Power Party from the Financial Services Commission on September 15, out of a total of 1,112 designated innovative financial service cases, 560 were related to network separation at financial firms. This accounts for 50.4% of all cases. Of these 560 network separation service cases, 366 involved "use of internal network for cloud-based software (SaaS)," while 193 involved the designation of services allowing the use of generative artificial intelligence (AI) within internal networks at financial companies. Network separation refers to the regulation requiring companies to physically separate their internal business networks from external internet networks, to prevent external breaches. Financial firms have argued that it is difficult to utilize generative AI as part of their work due to these network separation regulations, and that the rules are inefficient in development and testing. They have consistently called for loosening such measures. There have also been 54 cases related to partial share trading (both domestic and overseas), another major complaint frequently raised by large securities companies.
In particular, this year has seen a high number of service designations related to the relaxation of regulations on the financial sector. Of the 114 innovative financial service cases designated in 2026, 89 were related to regulatory easing. Specifically, there were 44 cases for network separation, 30 involving regulatory easing for online investment-linked financial business (P2P lending), and 15 concerning the relaxation of regulations for credit card companies and cooperatives.

By contrast, only 31 cases related to blockchain—considered a representative innovative technology—have been designated over the past seven years, covering fractional investment and unlisted stock trading, among others. Additionally, there have been cases where companies were designated as innovative financial services but failed to actually launch their services. For example, in December 2024, 18 financial institutions applied to have their retirement pension robo-advisor discretionary services, which use AI algorithms to automatically manage retirement pension assets, designated as innovative financial services. Of these, only 10 companies actually launched services, while the remaining 8 did not.
Despite the possibility of relaxing regulations by other means, concerns have been raised that the sandbox is being reduced to a complaint-handling channel for financial firms, potentially leaving truly innovative fintech services excluded. For instance, regarding the use of SaaS in internal networks, most financial firms received service designations after applying for approval as innovative financial services in December last year. However, an amendment to the Electronic Financial Supervision Regulations in April this year allowed financial firms to use SaaS within internal business networks. Some are saying that because only the timing differed, services that were already set to be deregulated were being designated, possibly at the expense of more innovative services. An industry insider commented, "Even the committee members responsible for screening innovative financial services are asking whether we need to go out of our way to review issues such as network separation for major financial institutions in the sandbox, when there is nothing truly new."
Hot Picks Today
 Police Give 70,000 Won of Their Own Money to Homeless Man in His 40s Who Stole Two Bags of Potato Rice Cakes Out of Hunger
- Assets Under Management Surge 380-Fold in a Year: "This Is Why the KOSPI Is Volatile," BIS Issues Dire Warning
- "Better Than Adults": Fourth Grader Shows Responsibility After Scratching Car While Riding Bicycle
- "He Likely Felt a Sense of Crisis—He Might Die"... Why Kim Jong Un Is Rushing to Name His 13-Year-Old Daughter Successor
- "This Is a Must-See"...Tourism Industry in Japan Hits 4-Trillion-Won Jackpot
There are two main reasons financial institutions favor the innovative financial service designation over legal amendments. First, it confers exclusive operation rights. When regulations are relaxed via revised rules or guidelines, similar benefits are made available to all financial institutions. In contrast, designation as an innovative financial service provides exclusive operation rights for up to two years under the Special Act on Financial Innovation Support. This prevents latecomers from launching the same service. The second reason is speed. Legal amendments require numerous steps, such as party-government consultation, inter-ministerial coordination, legislative review, and public notice, all of which are time-consuming. By contrast, designation of innovative financial services can be completed within 120 days after document submission, working-level review, and Resolution by the Innovative Financial Review Committee.
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.