Why Are Activist Funds Eyeing Korea? The Gap Created by the "Korea Discount"
Even Short-Selling Specialist Safkhet Shifts to Long Activism
Commercial Act Reforms Drive Structural Change in Korean Market
Foreign Capital Sees Investment Opportunity
"Increased Capital Inflow Brings Korea Closer to Global Standards"
The growing focus of foreign activist funds on the Korean market is largely attributable to expectations that the “Korea discount” will finally be addressed. In the past, the Korean stock market was undervalued due to chronic weaknesses such as low shareholder returns, complex ownership structures, and decision-making centered on controlling shareholders. Recently, however, investors have begun to see these weaknesses as investment opportunities. Amendments to the Commercial Act, new requirements obligating cancellation of treasury shares, and the Value-Up program are among the institutional changes increasing the justification for demanding value improvement from undervalued companies.
"Now is the cheapest time"... Korea's Changing Market Landscape
According to financial authorities as of September 11, under the Lee Jae-myung administration, there has been a series of capital market reforms aimed at protecting minority shareholders and enhancing corporate value. The Financial Services Commission has revised regulations in accordance with the amended Commercial Act, requiring listed companies to make broader disclosures on their holdings and plans for dealing with treasury shares. The intention is for treasury shares to serve as a medium- and long-term means to boost corporate value, rather than simply being used for short-term stock price management or as a defense against hostile takeovers.
Furthermore, starting this November, financial authorities plan to announce companies that, among the 11 sectors classified by the Global Industry Classification Standard (GICS), have maintained a price-to-book ratio (PBR) in the bottom 25% for KOSPI and the bottom 10% for KOSDAQ for three consecutive years. This is essentially an official move by the government to pressure companies whose share prices are excessively low relative to their assets.
These changes are providing activist investors with even greater justification to target the Korean market. In the past, it was difficult for external shareholders to challenge issues like treasury share holdings, low dividends, or complex ownership structures. Now, however, as requirements for canceling treasury shares, board accountability, and protecting minority shareholders have entered the institutional mainstream, activist funds have more space to make their demands.
There is also analysis within the securities sector that domestic activism is evolving from merely calling for shareholder returns to broader issues such as board composition and capital allocation. According to the “Governance Impact” report published last month by Hanwha Investment & Securities, demands for board entry accounted for 24.7% of domestic activist campaigns launched from 2025 through the first half of 2026—the highest share and up 13.8 percentage points from before 2025. In contrast, the percentage of campaigns focused on shareholder returns declined by 7.9 percentage points during the same period. Park Seyeon, a researcher at Hanwha Investment & Securities, analyzed, “Activist demands are expanding beyond short-term returns such as dividends and treasury shares to long-term issues requiring continued execution, such as board composition, capital allocation, and strategic changes.”

After the Japan Experience, Korea Is the "Next Market"
Foreign asset managers’ perspectives on Korea are also shaped by recent events in Japan. In recent years, Japan has been a major stage for global activist funds. Hanwha Investment & Securities analyzed that the number of global activist campaigns reached an all-time high of 765 in 2025, with much of this rapid growth shifting to Asia. Of the 163 new global activist campaigns between 2018 and 2025, 81% occurred in Japan, and including Korea, the total for the two countries rises to 92%. Researcher Park commented, “Korea is currently in the early stages, trailing Japan by about five to seven years.”
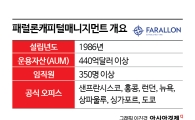
Farallon Capital Management, which is considering entering the Korean market, is an asset manager that has already capitalized on a similar market evolution in Japan. In 2022, as the third-largest shareholder holding more than 6% of Toshiba shares, Farallon opposed the company’s breakup plan and publicly demanded that sale proposals be considered. At the time, Farallon criticized Toshiba for pursuing the breakup plan without sufficiently reviewing alternatives, such as a private equity buyout.
The case of Astellas Pharma is also notable. According to major foreign news outlets, last year Farallon acquired more than a 3% stake in Astellas Pharma, a leading Japanese pharmaceutical company, and, as a top shareholder, called for cost reductions, a review of research and development strategies, and a reassessment of the company’s mergers and acquisitions (M&A) strategy.
Even Short-Selling Specialists Are Shifting to "Long Activism"
The case of Safkhet Capital is a symbolic example of the Korean market’s changing status. Fahmi Quadir, founder and Chief Investment Officer (CIO) of Safkhet Capital, who is widely known as a short-selling specialist, has chosen Korea as her new investment stage. She rose to prominence with short-selling strategies targeting accounting and governance issues at companies such as Canada’s Valeant Pharmaceuticals and Germany’s Wirecard, betting on share price declines. However, in Korea, instead of attacking troubled firms to bet on share price drops, she has shifted direction—acquiring undervalued companies and demanding improvements in corporate governance and shareholder returns.

Market participants interpret these developments as a sign that Korea is no longer just an inexpensive market, but one "with the potential for change." Without institutional catalysts to resolve undervaluation, activist funds could be locked in for the long term. But, with ongoing regulatory reforms and improvements in the perception of shareholder capitalism, there is now room for success. Already the Korea Value-Up Index, launched by the Korea Exchange, has risen 85.2% so far this year—outperforming the KOSPI’s 66.9% return as of the previous day.
Namwoo Lee, Chairman of the Korea Corporate Governance Forum, explained, “If the ‘Korea discount’ has long been a weakness of the Korean market, the moment this weakness begins to change is an ideal investment opportunity for activist funds. The more foreign activist capital flows in, the more Korea’s market will inevitably align with global standards and the lower share price volatility will become.”
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.