[Click e-Stock] IBK Investment & Securities: "COSRX Drives Growth for Amorepacific"
"Sales Expected to Rise 29.2% Year-on-Year This Year"
Coverage Initiated with Target Price Set at 200,000 Won
On September 1, IBK Investment & Securities initiated coverage of Amorepacific, setting a target price of 200,000 won, which is 32.8% higher than the closing price of 150,600 won as of August 28, and assigned a 'Buy' investment rating.
Jin Cho, analyst at IBK Investment & Securities, stated, "Amorepacific operates more than 30 diverse skincare brands and continues to achieve solid sales growth in its core haircare product lines." He added, "Domestically, sales growth is now driven by online and MBS (multi-brand shop) channels, moving away from the previous emphasis on duty-free and offline road shops. Internationally, the company is restructuring its sales channels by expanding into e-commerce platforms, shifting from its traditional focus on offline distribution networks."

In particular, he identified 'COSRX' as a key brand that has entered a robust sales growth trajectory. Last year, COSRX underwent business restructuring, including revamping its distribution structure and pricing policy, resulting in a 22.6% year-on-year decline in sales. However, starting from the fourth quarter last year, the effects of the renewal began to emerge, with sales rebounding to 152.3 billion won and operating profit reaching 38.1 billion won. This year, sales are estimated to grow by 29.2% year-on-year to reach 589.6 billion won. Cho noted, "Unlike in the past, when the company was heavily dependent on a single product, the diversification of SKUs through new lines such as the RX line has enabled COSRX to successfully achieve a turnaround." He also projected, "As a high-margin brand with an operating profit margin in the 20% range, COSRX is expected to contribute significantly to the company's overall profitability."
Hot Picks Today
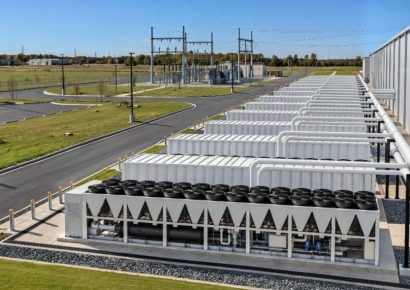 "The Real Winner Controls the Heat"...LG Electronics Bets 150 Billion Won on New Chiller Plant in Virginia, US
- SK hynix Maintains 3.4 Million Won Target Price: "Strong Memory Demand" [Click eJongmok]
- SNU Students Line Up for This Recruitment Fair: "Better Than Large Corporations" [Report]
- Minister Kim Jonggwan: "US Investments Will Not Shift to 9-to-1 Profit-Split Until Full Recovery of Principal and Interest"
- "Did They Really Use That Pot for Cooking?" Outrage as Chinese Kindergarten Caught Washing Rags in Kitchen
He further commented, "Amorepacific has historically traded at a discount compared to industry peers due to China exposure and earnings volatility. However, the proportion of the China region has now shrunk to 10.6% of overseas sales, and the completion of restructuring has made downside risk to profits limited. The meaningful increase in Western market sales and the growth of derma brands are promising developments. With the operating profit margin stabilizing in the 10% range, the justification for the discount has weakened."
© The Asia Business Daily. All rights reserved. Unauthorized AI training and use prohibited.